(3 min read)
The UK financial services sector continues to face a changing regulatory environment, bringing both opportunity and uncertainty. This issue explores recent developments in consumer finance, including progress on the reform of the Consumer Credit Act 1974, the FCA’s work on mortgages and open finance, and recent case law on unfair relationship claims. Firms involved in retail financial services, consumer credit and adjacent markets should track these changes closely, consider how the changing legal and regulatory landscape may affect their operating models, risk frameworks and delivery of financial products and services, and take early steps to prepare.
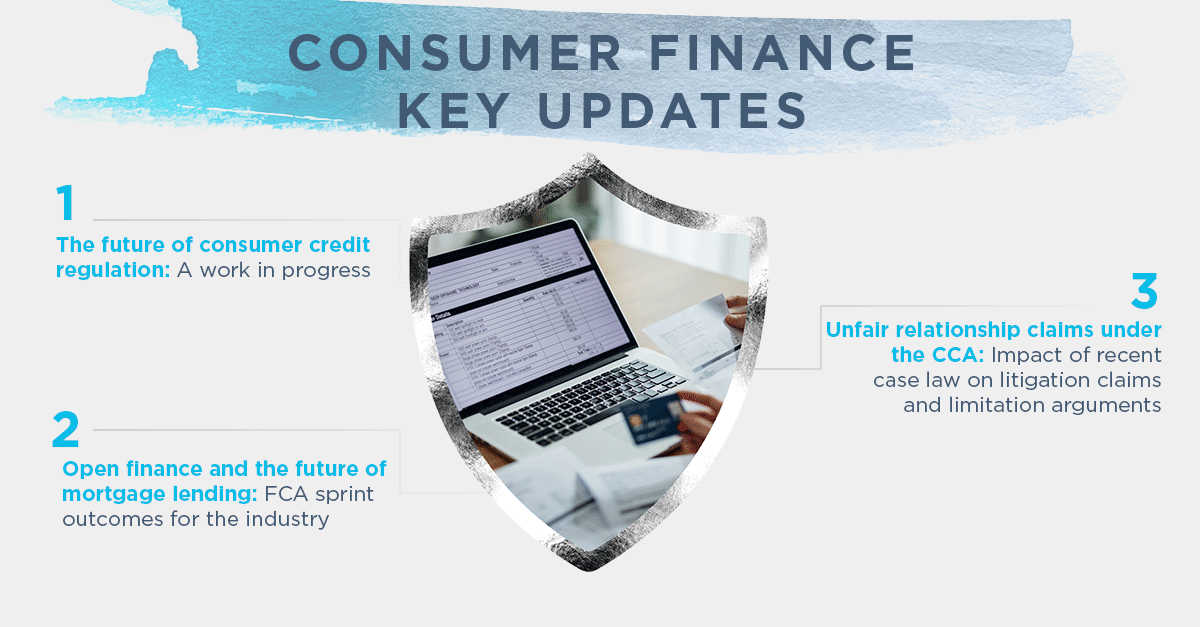
The future of consumer credit regulation: a work in progress
The legislative foundations for the reform of the Consumer Credit Act 1974 (CCA) are still taking shape, as the proposed changes continue to be tested and refined during the passage of the Financial Services and Markets Bill 2026 through the UK Parliament. The shape of the reform that will follow will define consumer credit regulation for years to come. In this article, we examine how the CCA reform proposals are progressing through Parliament and discuss a new amendment to the Bill that is likely to impact the timing and the transparency of the Financial Conduct Authority’s (FCA) exercise of its new consumer credit powers.
Please click here to learn more on the passage of the reform
Open finance and the future of mortgage lending: FCA sprint outcomes for the industry
The FCA has recently published a report summarising outputs from its mortgages and open finance policy sprint, which examined how open finance could improve mortgage journeys. The sprint outputs show that the debate has moved far beyond whether open finance could improve mortgage journeys and is instead focused on the enabling conditions. Although the report makes no formal recommendations or rules, it provides a clear indication of the direction of future regulatory expectations.
Please click here to learn more on the findings from the Sprint
Unfair relationship claims under the CCA: impact of recent case law on litigation claims and limitation arguments
Unfair relationship claims under sections 140A–C of the CCA are now a firmly embedded feature of the UK litigation landscape, appearing before the courts with striking regularity as claimants continue to probe the limits of what amounts to an “unfair” credit relationship. For lenders, this is a dynamic and evolving area: judicial interpretation is far from settled, and keeping pace with recent decisions is critical to effective litigation risk management. In this issue, we examine two recent cases that vividly demonstrate how the law in this area is developing and what that means in practice for litigation claims generally and limitation arguments.
Please click here to read our analysis of the cases
Upcoming events
For information on our upcoming training events including our Regulatory Essentials programme, please visit our Financial Regulation page on our website.