How does the new AMLAR Strategy change the risk of intervention for financial institutions?
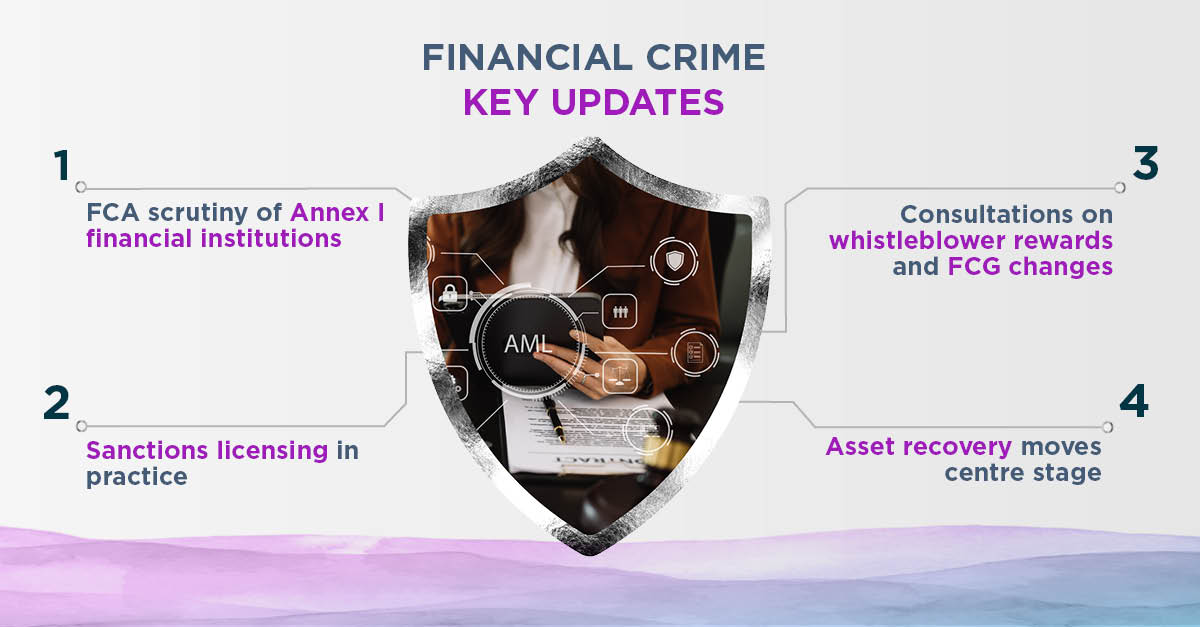
The Anti-Money Laundering and Asset Recovery (AMLAR) Strategy 2026 to 2029, published by HM Treasury and the Home Office on 15 September 2026, makes asset recovery a core pillar of the UK's response to economic crime. Under it, the role of the authorities will gain prominence. A defence to the principal money laundering offences in Part 7 of the Proceeds of Crime Act 2002 (POCA) does not protect against Part 5 civil recovery powers or account freezing orders over customers' funds. Recent cases show that working capital can be frozen even where the customer has done nothing wrong, and that a documented suspicion can form part of the evidential basis for an order. The Strategy is backed by additional funding for Crown Prosecution Service civil recovery, National Crime Agency-hosted forensic accounting and tracing specialisms, and a new National Financial Intelligence Service. For firms, the risk profile shifts towards more account freezing, disclosure and recovery orders, often driven by intelligence they cannot see.
(5-min read)
Read our full analysis of the AMLAR Strategy here
The AMLAR Strategy shifts exposure from liability for laundering to operational, reputational and conduct risks at the point of intervention, requiring practical action by firms. For support with new procedures, please reach out to the authors.
Increasing FCA focus on Annex I financial institutions
Over the course of 2025 and 2026, the FCA has increased its focus on ‘Annex I financial institutions’ – financial services firms that are not (and are not required to be) fully authorised and regulated by the FCA and/or PRA, but still need to be supervised by the FCA for the purposes of anti-money laundering, counter-terrorism and proliferation financing. This increased focus is resulting in live risks for such firms and those that deal with them.
(5-min read)
Here, we explore why registration as an ‘Annex I financial institution’ is the start, not the end, of MLR compliance, and how the FCA is now testing both registered and unregistered firms
What is an ‘Annex I financial institution’?
Whether a financial services firm is an ‘Annex I financial institution’, and what it needs to do when it is, are, in our experience, sometimes poorly understood issues.
Underlying them is a technical point: how the perimeter of the Money Laundering, Terrorist Financing and Transfer of Funds (Information on the Payer) Regulations 2017 (MLRs) relates to the (legally distinct) perimeter of financial services regulation in the UK created by the Financial Services and Markets Act 2000 (FSMA).
In short, under English law as it currently stands, the perimeter of the MLRs (which derives from EU law prior to Brexit) is in some respects wider than the perimeter of FSMA.
- Financial services firms that carry on FSMA regulated activities need to be fully authorised and regulated by the PRA and/or FCA. They will generally also be within scope of the MLRs, but will be supervised by the FCA for AML purposes as part of their broader regulatory relationship. They do not need to make a separate application to the FCA for registration as an Annex I financial institution.
- The MLRs also cover a material group of firms that do not carry on FSMA regulated activities and so do not require authorisation by the PRA and/or FCA under FSMA, but carry on other financial services that still bring them within scope of the MLRs. This group of firms are ‘Annex I financial institutions’ and must still register with the FCA for AML supervision.
- The MLRs also cover: (i) a broad group of professional services (law, accountancy, audit) firms that are currently supervised by professional bodies but in time will also be supervised by the FCA; as well as (ii) a broad group of non-financial services firms such as estate agents and lettings agents, high-value dealers, casinos and others that are not supervised by the FCA (but by other authorities instead, particularly HMRC). We reference these for completeness only. These types of firm are not Annex I financial institutions.
Which firms are most at risk of being an Annex I firm?
The perimeter of the MLRs is a complex issue and a close analysis is usually required to determine whether a firm’s activities bring it within scope (and if so, which is the appropriate supervisory authority).
In broad terms, however, firms that may have determined they do not need to be authorised under FSMA, but are still at risk of being an ‘Annex I financial institution’ include:
- commercial lenders (i.e. those not involved in FCA-regulated consumer credit, which requires full authorisation under FSMA). This includes commercial property / real estate lenders and some asset finance firms, particularly where their activities include carrying on lending and financial leasing (but not pure operational leasing);
- some firms that are involved in securities issues, safe custody and money broking; and
- some corporate finance and M&A advisory firms.
Some special-purpose vehicles may also be ‘Annex I financial institutions’, typically where they act as an original lender or financial lessor.
What are the key risks for ‘Annex I financial institutions’?
Over 2025 and 2026, the FCA has increased its scrutiny of firms already registered with it as ‘Annex I financial institutions’. For example, in August 2026, the FCA issued a statement noting it had over the previous year issued information requests to all 1,200 or so firms already registered with it, including requests for information about their activities, business models and risks.
Firms that have already registered with the FCA as ‘Annex I financial institutions’ need to be aware that compliance with the MLRs does not end with registration. They will be expected to be compliant with the MLRs’ many other requirements on an ongoing basis, including with respect to risk assessment, policies, controls and procedures, customer due diligence, ongoing monitoring, suspicious activity reporting, and staff training. Failure to comply with these requirements is a breach of the MLRs that can carry with it civil and/or criminal consequences. The FCA has a wide range of supervisory and enforcement powers available to it, including powers to require information, powers to give directions that can be used to limit firms’ ability to do business, and powers to investigate and sanction breaches of the regulations.
Carrying on financial services business that is in scope of the MLRs (but not FSMA) without registering with the FCA as an ‘Annex I financial institution’ is a breach of the MLRs in its own right, and can also carry civil and/or criminal consequences. Failure to register can also result in issues with customer agreements and other business disruption. In some cases, directors and officers can also be personally at risk.
In March 2026, the FCA issued a reminder to FSMA-regulated (i.e. fully authorised) firms about dealing with ‘Annex I financial institutions’ including of the need to undertake due diligence (“proper checks”) on them. Fully-regulated firms – in our experience, often bank funders – who find themselves dealing with counterparties that are, or may be, ‘Annex I financial institutions’ – can face a number of potential issues. These include potential contractual risks, risks of regulatory criticism for weaknesses in their own control environments, and risks of increased exposure to the proceeds of crime.
Resolving Annex I issues
For some financial services firms, determining whether they are an ‘Annex I financial institution’ is not an easy task. Some firms’ activities may legitimately be outside both FSMA and the MLRs. Some activities may span the perimeter of the MLRs. Occasionally, on closer analysis, some may also be found to span the perimeter of FSMA. As explained above, there can be serious consequences for firms that don’t get the analysis right. We therefore encourage firms that are unsure whether they qualify as an ‘Annex I financial institution’, or are concerned that they may be but are not currently registered with the FCA, to act on those concerns and, if need be, take advice.
Moreover, the process of applying to register as an ‘Annex I financial institution’ can itself be onerous. In October 2026, the FCA refreshed its webpage on registration, emphasising the preparation and documentation that is needed for a successful application. The FCA has also made clear that it is scrutinising applications closely and that applications are taking longer as a result.
On a positive note, however, in our experience, firms faced with complex ‘Annex I financial institution’ issues can often mitigate or manage them effectively by taking a proactive approach.
If you are facing challenges in this area, for example a lack of clarity over whether your firm is an ‘Annex I financial institution’, a challenging registration process, or intervention action by the FCA, please get in touch with the authors.
Proposed reform of the UK’s whistleblowing framework
In October 2026, the UK government opened a consultation on proposed amendments to the law of whistleblowing, which if they proceed would be of wide application (both in financial services and beyond). Perhaps the most controversial aspect is the SFO's proposal, which the government is taking forward, to introduce a scheme to reward whistleblowers who report economic crime. The consultation remains open until January 2027.
(5-min read)
Here, you can find our summary of the consultation on paying whistleblowers a share of corporate economic crime penalties:
What is the government consulting on?
In summary, the UK government is proposing to update the existing whistleblowing framework in the Employment Rights Act 1996, and is seeking views (among other matters) on:
- whether the UK’s current whistleblowing protections apply to a wide enough group of individuals;
- whether the ‘disclosure in the public interest’ test (part of the UK’s current test for a whistle blow) is too vague / open to interpretation, or is flexible and operating effectively;
- whether the current list of types of wrongdoing that define a whistle blow is appropriate or requires updating, particularly in an age of challenges posed by ‘frontier AI’;
- whether additional disclosure routes are required / whether the law should be amended to create a new protected disclosure route; and
- whether reforms are needed to promote enforcement and to make it easier for those able to blow the whistle to identify the appropriate target for the disclosure.
Following on from a recommendation by Jonathan Fisher KC’s July 2026 Fraud in the Digital Age Independent Review of Disclosure and Fraud Offences, the government is exploring replacing the existing model with an incentivisation scheme to reward whistleblowers regarding economic crime. One key driver is the perceived intelligence drain in favour of overseas intelligence agencies, the goal being to deliver a powerful commercial reason to report wrongdoing directly to UK authorities first.
What is the SFO's proposed whistleblower reward scheme?
In summary, it is proposed that:
- a scheme should be introduced to reward whistleblowers for ‘significant and original’ information that leads to a ‘successful enforcement outcome’ against a company, such as a criminal conviction or a Deferred Prosecution Agreement;
- the reward should be funded from the financial penalty / fine paid by the company;
- the SFO should be responsible for determining eligibility for awards and the amount awarded (based on a percentage of the financial penalty or fine imposed on a company);
- the scheme should be supported by new criminal offences (for example a new offence of harassing or intimidating whistleblowers who report information under the SFO’s scheme);
- the SFO should publish an annual report on the scheme.
Some of the considerations around this include the risk that multi-million-pound incentives will encourage employees to bypass internal reporting systems, reducing the ability of organisations to investigate internally and address any issues. In addition, there is a risk of an increase in low-quality, speculative reports, and pressure on the SFO to filter these out from useful intelligence reports. Finally, there are questions over the extent to which implicated whistleblowers should receive financial benefits from making relevant reports.
However, the government is consulting on all of these issues, with the consultation remaining open until January 2027.
Please contact the authors if you would like assistance with this; we will be happy to support clients through their consultation responses.
CP 26/38: Proposed changes to the FCA’s Financial Crime Guide (FCG)
In October 2026, the FCA opened a consultation on proposed amendments to its Financial Crime Guide, to reflect insights from its supervision and also wider developments. Although the consultation does not implement specific new Handbook rules, the guidance that the FCA publishes is material to their interpretation, and there are a considerable number of proposed changes. Overall, these cover fraud, crypto assets, financial and trade sanctions, proliferation financing, data security, and systems and controls as well as terrorist financing. The consultation closes on Christmas Eve 2026.
(2-min read)
Some highlights from the consultation
In our view, highlights within the proposed new guidance include:
- new guidance on APP fraud, money muling and romance fraud;
- new guidance concerning enhanced due diligence, systems and controls relating to crypto assets;
- an updated view from the FCA of good and poor practice on financial and trade sanctions, including on risk assessments, customer due diligence and ongoing monitoring;
- new guidance on governance expectations around data security; and
- new guidance on how the FCA sees financial crime obligations applying in relation to Banking as a Service.
Clients old and new are welcome to contact the authors for further discussion about the changes.
UK sanctions: trade enforcement and circumvention risks move front and centre
The second half of 2026 has continued to sharpen the practical UK sanctions risk for financial institutions. The key developments are not simply additional names on the UK Sanctions List. They show UK authorities and regulators moving further into the mechanics of circumvention: how higher-risk goods reach sanctioned destinations, how those transactions are financed, and whether firms’ systems can withstand a sudden increase in designations and alerts. The priority remains to connect sanctions screening with customer due diligence, trade finance controls and transaction monitoring, rather than treating list screening as a complete answer.
The most important developments for financial institutions are the new sanctions end-use controls, renewed restrictions on Iran and an October package targeting Russia-linked oil, payments, crypto and military supply chains. This sits alongside the FCA’s proposed changes to the Financial Crime Guide, also discussed above.
(5-min read)
Why do the new UK sanctions end-use controls matter to financial institutions?
The Sanctions (EU Exit) (Miscellaneous Amendments) Regulations 2026 first introduced targeted sanctions end-use controls across relevant UK trade sanctions regimes in May 2026. OTSI’s first annual review, published on 27 August 2026, brought this new power into sharper practical focus. Where the government informs a UK exporter that specified goods or related technology may be diverted through a third country to a sanctioned destination or person, the exporter must obtain a licence before proceeding. The control applies to goods and related technology that are not already covered by the UK’s strategic military or dual-use controls, and breach after an informing notice can result in civil or criminal enforcement.
Although the immediate legal trigger is directed primarily at the exporter, the regulatory focus extends to the services that enable higher-risk trade, including its financing. OTSI has said that its enforcement work examines services-enabled trade diversion and activity involving UK intermediaries, while its first annual review records that the majority of reports to OTSI came from the financial services sector. Banks should therefore expect increasing scrutiny of whether they understand how trade-facing customers identify controlled goods, assess diversion risk and respond to an informing notice or licensing requirement.
In practice, firms may need to identify customers and facilities exposed to higher-risk industrial goods, Common High Priority items and diversion routes through third countries; obtain credible information on goods, commodity codes, end users, end use and shipping routes; ask customers to notify the bank promptly if they receive an informing notice; and ensure that trade finance, payment and relationship-monitoring teams can recognise unexplained changes in destinations, counterparties, product descriptions or payment flows. Where this is necessary, documentation should show not only that the customer and counterparties were screened, but why the underlying trade and financing made commercial sense.
What does the FCA’s proposed Financial Crime Guide mean for sanctions controls?
As stated above, the consultation does not propose new rules but would update non-binding guidance to clarify existing expectations. Within the sanctions proposals, the FCA expressly plans to clarify firms’ responsibilities when using third-party screening tools or outsourced arrangements, including oversight of vendor-configured settings and the timely, complete and accurate implementation of sanctions-list data. Separately, the wider money-laundering and terrorist-financing proposals say that firms using artificial intelligence and other third-party tools remain accountable for the financial crime risks those tools present; the tools should be proportionate to the firm’s risk profile and risk appetite, and subject to testing and validation. Read together, the proposals reinforce that firms should not treat vendor or AI output as a black box: they need effective governance over configuration, data quality, changes and assurance.
The proposed sanctions guidance also goes materially beyond name screening. It asks firms to consider exposure arising from customers, counterparties, intermediaries, jurisdictions, goods, services, transactions, payments and payment messages, and specifically encourages monitoring of risks associated with goods, vessels, ports, services and jurisdictions.
The customer due diligence proposals include ownership structures, connected parties, counterparties and relevant trade information, while the evasion material refers to typologies, data analysis, thematic review and transaction monitoring.
Proliferation financing is addressed separately but linked closely: the FCA recognises that it may use mechanisms similar to sanctions evasion and proposes guidance on strategic export controls, dual-use and military goods, and integrating proliferation-financing risk into onboarding, customer due diligence, screening and transaction monitoring.
In practice, firms should map these proposed expectations against their sanctions risk assessment, identify gaps in vendor oversight and non-name screening, and test whether trade-finance and payment controls use the information collected during customer due diligence.
What other changes should firms prioritise?
Iran. In September 2026, the UK expanded its financial, trade and transport restrictions against Iran. The new measures include prohibitions relating to loans, credit and investment, further restrictions on banking relationships and market access, an insurance ban and restrictions on Iranian sovereign bonds. They also extend trade controls across energy, precious metals, maritime goods, oil, gas, petrochemicals and sectoral software, including associated financial services, brokering and certain indirect or third-country activity. Firms should refresh Iran-related country and sector risk assessments, customer and payment rules, securities controls, insurance restrictions and trade finance questionnaires, rather than relying on older assumptions. Again, a particular focus on trade activity is needed, against the ongoing background of the potential impact of the UK’s blocking legislation.
Russia circumvention. On 8 October 2026, the UK designated 38 new organisations on the UK Sanctions List including oil companies, shadow-fleet tankers, crypto exchanges, payment platforms and suppliers of Common High Priority goods, on the basis of circumvention activity relating to Russia. The package is relevant beyond name screening: it targets payment and crypto routes, oil-trading networks and third-country supply chains used to disguise the movement of military-relevant goods. Relevant financial institutions may need to review exposure to newly designated entities and vessels, but also fine-tune monitoring tools for linked wallets and payment platforms, opaque changes in vessel or trading counterparties, and customers whose trade with higher-risk intermediary jurisdictions is inconsistent with their stated business.
Financial institutions can use these developments to test whether sanctions risk assessments, customer due diligence, trade finance controls, payment screening and alert governance operate as one combined framework or remain fragmented across systems. Priority reviews should focus on trade-facing customers, higher-risk third-country routes, payment-chain screening and escalation capacity. Please contact the authors if you would like to benchmark those controls or assess a specific customer, facility or transaction.
Frequently asked questions
Does a firm registered with the FCA as an Annex I financial institution need to do anything further?
Yes. Registration does not end MLR compliance: the firm must meet ongoing requirements on risk assessment, policies and controls, customer due diligence, monitoring, suspicious activity reporting and training.
Can a commercial lender be an Annex I financial institution without being FCA-authorised?
Yes. Commercial lenders outside FCA-regulated consumer credit, including some real estate and asset finance lenders, may fall within the MLRs while sitting outside FSMA authorisation.
What should banks do when funding an Annex I financial institution?
The FCA reminded authorised firms in March 2026 to undertake "proper checks" on Annex I counterparties, to manage contractual, regulatory and proceeds-of-crime risks.
How would the SFO's whistleblower reward scheme be funded?
It is proposed that rewards would be a percentage of the financial penalty or fine paid by the company following a successful enforcement outcome, such as a conviction or a Deferred Prosecution Agreement.
Can an account freezing order be made where the account holder has done nothing wrong?
Yes. Recoverable property can be traced into the hands of third parties, and protection for good-faith recipients is lost once they are on notice that funds may be recoverable.