The CP builds on existing frameworks such as the Taskforce on Climate-related Financial Disclosures (TCFD) and is designed to be flexible in light of the UK's forthcoming "green taxonomy" and incorporate developments in other global standards' regimes (e.g. further work by the International Sustainability Standards Board (ISSB)). The development of relevant standards will of course be crucial to develop high quality reference points around the concept of a "credible standard" of "environmental and/or social sustainability" that "Sustainable Focus" labelled funds will be able to benchmark their investment objectives and policies against. At this stage, the CP contains details around the attributes of such a standard, rather than designating a limited range of reference points.
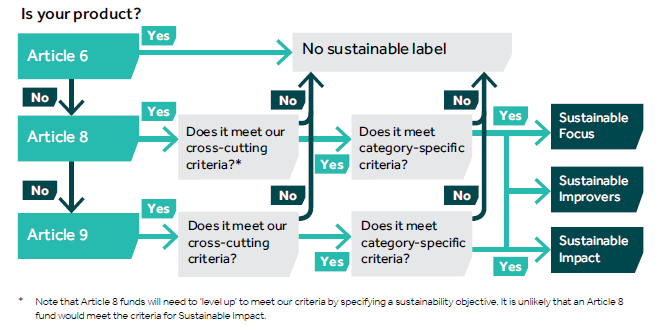
The FCA has considered the CP regime's international coherence with both SEC proposals and SFDR, and has indicated how funds classified under those regimes may map onto the FCA proposals. Retail fund managers in the UK will no doubt be familiar with the SFDR, which also creates three categories of funds:
- Article 6: funds that do not integrate sustainability into the investment process;
- Article 8: funds that promote, among other characteristics, environmental or social characteristics, or a combination of those characteristics, provided that the companies in which the investments are made follow good governance practices ("light green" funds); and
- Article 9: funds that have sustainable investment as their objective ("dark green" funds).
Fund managers should take note that the FCA (i) does not consider that ESG integration to be "a sustainable investment strategy" in its own right; and (ii) has not incorporated the "Do No Significant Harm" (DNSH) or "Principal Adverse Impact" (PAI) concepts located within the SFDR. The most analogous part of the regime to DNSH is the concept of "unexpected investments" in terms of the disclosure requirements within the CP.
Whilst the FCA has sought to avoid inconsistences with the SEC and SFDR regimes, the three regimes do not map directly across. The FCA has, however, provided the following helpful flowcharts, which firms can refer to in order to assist them in mapping existing funds which are in-scope of SFDR (i.e., Article 6, 8 and 9 funds) and the SEC's three ESG fund categories (i.e., integration funds, ESG-focused funds and impact funds):
SFDR
SEC proposals
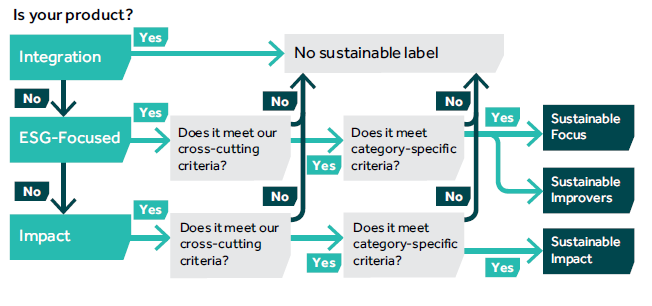
Pg. 83, CP. © The Financial Conduct Authority.